Blostem × DCB Bank Partnership Launch at GFF 2026: DCB Bank FDs Now Available on the Blostem SDK
DCB Bank fixed deposits are now live on the Blostem SDK. Fintech apps can offer DCB Bank FDs online through one API integration. Launched at GFF 2026.
Key takeaways
- DCB Bank fixed deposits are now live on the Blostem SDK, launched at Global Fintech Fest 2026.
- Fintech, wealth and consumer apps can offer DCB Bank FDs online through one API integration.
- Platforms already on the SDK can switch DCB Bank on through configuration, with no new build.
- DCB Bank deposits carry DICGC cover up to Rs 5 lakh per depositor per bank.
DCB Bank Digital Fixed Deposits: What Went Live at GFF 2026
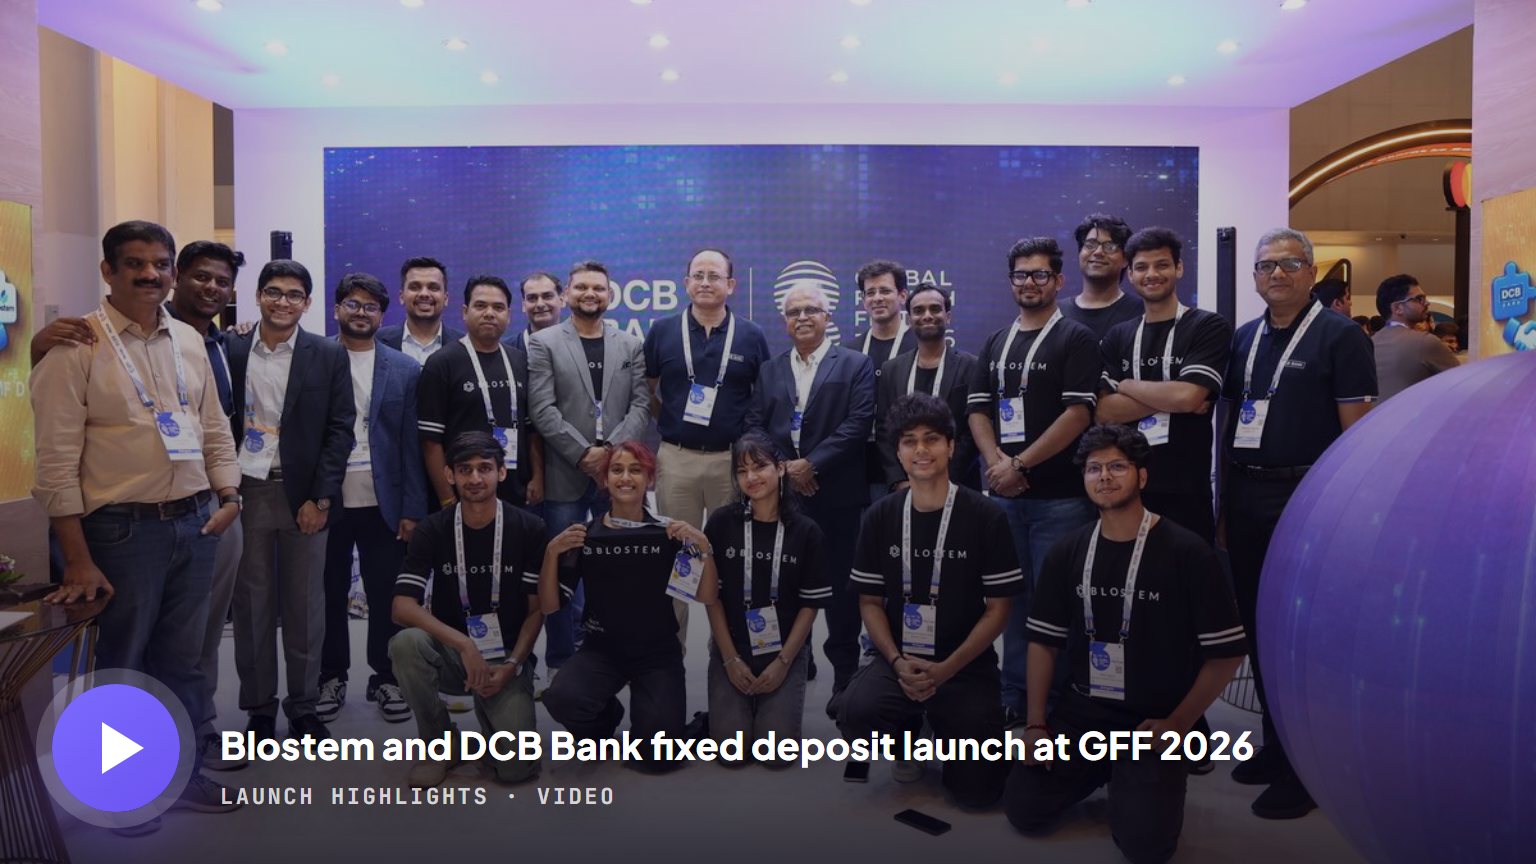
Blostem and DCB Bank fixed deposit launch at Global Fintech Fest 2026, partnership highlights. Opens on LinkedIn.
DCB Bank joins Blostem's issuer network as a scheduled commercial bank, adding branch-backed deposit products alongside the small finance banks and NBFCs already on the platform. The announcement was made at Global Fintech Fest 2026, held in Mumbai from 9 to 11 September 2026, where Blostem exhibited at Booth J18 and J20 in Pavilion Hall and ran the end-to-end deposit journey live for visiting teams.
In practical terms, a depositor inside a partner application can now discover a DCB Bank fixed deposit, complete the bank's verification requirements, fund the deposit and hold it in their portfolio without leaving the partner's brand. Nothing about the journey routes the user to a separate bank website or a separate app.
For platforms already live on the Blostem SDK, DCB Bank is available as a configuration change rather than a release. No new engineering work, no new integration, no app store cycle. Indian Overseas Bank also went live on the Blostem SDK at GFF 2026.
Why DCB Bank Fixed Deposits Matter
For a distribution partner, an issuer's regulatory standing and operational depth matter more than a headline rate. DCB Bank brings both.
- 480 branches across India, as on 30 June 2026
- 3.2 million+ active customers
- 21 states and union territories covered by the branch network
- Roots in India since the 1930s
DCB Bank is a new generation private sector bank and a scheduled commercial bank regulated by the Reserve Bank of India. Its promoter and promoter group, the Aga Khan Fund for Economic Development and Platinum Jubilee Investments Limited, hold a 16.24 per cent stake. The bank is registered with the Deposit Insurance and Credit Guarantee Corporation. (Source: DCB Bank.)
That profile changes the shape of what a partner platform can offer. Until now, the higher end of the rate range on most digital deposit marketplaces has come from small finance banks and NBFCs. Adding an established private sector scheduled commercial bank gives a depositor a genuine choice between institution types rather than a single category with different names on it.
What Is a Digital Fixed Deposit?
A digital fixed deposit is an ordinary term deposit with a bank, opened through an online journey inside an application rather than through branch paperwork. The deposit contract, the interest obligation and the deposit insurance are the same as a branch-opened deposit. What changes is the point of access.
Digital FD vs Branch FD at a Glance
| Digital FD | Branch FD | |
|---|---|---|
| How it is opened | Online journey inside a partner app | Paperwork at a bank branch |
| Who holds the money | DCB Bank | DCB Bank |
| Deposit insurance | DICGC cover up to Rs 5 lakh per depositor per bank | DICGC cover up to Rs 5 lakh per depositor per bank |
| KYC | Bank's KYC completed in the app, including video KYC where required | Bank's KYC completed at the branch |
| Interest rate and terms | Set by DCB Bank | Set by DCB Bank |
Two things are worth stating plainly, because they are the questions depositors ask most often.
The bank holds the money
The deposit sits on the issuing bank's balance sheet as a liability to the depositor. The fintech platform provides the interface. Blostem provides the distribution and technology layer between the two. Neither the platform nor Blostem holds the depositor's funds at any point in the journey.
Deposit insurance attaches to the bank, not the app
DICGC cover applies to eligible deposits up to Rs 5 lakh per depositor per bank, covering principal and accrued interest together. Because the limit is per bank, a depositor holding deposits at three different banks through the same app has three separate limits rather than one shared ceiling. That is a structural argument for multi-issuer distribution, not a marketing one.
How Fintechs Can Offer DCB Bank FDs Through the Blostem SDK
Blostem operates as the Business Correspondent and Technical Service Provider, which means a partner platform integrates once and inherits every issuer on the network. A single API integration covers the full deposit lifecycle:
- Discovery and comparison. Rates, tenures and issuer options surfaced in the partner's own interface.
- KYC and VKYC orchestration. Each issuer's verification requirements handled behind one flow.
- Payment and booking. Funding, confirmation and deposit advice generation.
- Portfolio and maturity tracking. Active and closed deposits, returns, maturity dates, renewal reminders.
- Servicing. Renewal, premature withdrawal, interest certificates and tax documents.
- Reconciliation and settlement. Operational plumbing between the platform and each bank.
The journey is fully white-label. Typography, colour, copy and feature toggles are configured per partner, so the deposit product reads as part of the partner's application rather than an embedded third party. Technical detail is in the Blostem SDK documentation, and the single integration model is covered at length in our engineering write-up.
Banks and NBFCs on the Blostem FD Platform
With DCB Bank live, the Blostem network spans private sector banks, small finance banks, a public sector bank and NBFCs:
- NEW

Issuer availability depends on the partner programme and the current issuer configuration. Deposit terms, tenures and rates are set by each issuing institution.
What the DCB Bank Launch Means for Fintech Platforms
If you already distribute deposits, this is a widening of the shelf at no integration cost. If you are evaluating whether to build deposits in-house, it is a reminder of what the build actually involves: every issuer added to a platform is a separate API surface, a separate KYC vendor relationship, a separate settlement process and a separate infosec review. That work does not end at go-live, it recurs for the life of the product.
- Wider rate and tenure spread to present to end users, across institution types rather than one category.
- Deeper DICGC headroom per depositor, since the limit applies per bank.
- No engineering cost for platforms already on the SDK.
- Under seven days partner go-live time for new integrations.
Teams comparing providers may find our fixed deposit provider comparison and build versus buy analysis useful before committing engineering time.
Frequently Asked Questions
Which banks and NBFCs offer fixed deposits through Blostem?
Blostem connects fintech platforms to fixed deposits from banks and NBFCs including DCB Bank, RBL Bank, Indian Overseas Bank, Unity Small Finance Bank, Suryoday Small Finance Bank, Utkarsh Small Finance Bank, Shivalik Small Finance Bank, Bajaj Finance, Shriram Finance and Mahindra Finance. Availability depends on the partner programme and current issuer configuration.
Are DCB Bank fixed deposits booked digitally covered by DICGC insurance?
DCB Bank is registered with the Deposit Insurance and Credit Guarantee Corporation. DICGC cover applies to eligible deposits up to Rs 5 lakh per depositor per bank, covering principal and interest together. The cover attaches to the bank holding the deposit, not to the app used to open it, and applies the same way whether the deposit is opened at a branch or digitally.
Can I open a DCB Bank FD online?
Yes. Fintech, wealth and consumer apps integrated with the Blostem SDK let depositors open a DCB Bank fixed deposit online, completing the bank's KYC inside the app journey. The deposit is held by DCB Bank in the same way as a branch-opened FD, and depositors can continue to use the bank's own branch and digital channels as well.
Do I need an existing DCB Bank account to open a fixed deposit through a partner app?
No. A depositor without a prior relationship with the bank can open a fixed deposit through a partner platform. The depositor completes the bank's full KYC as part of the journey, including video KYC where the bank's process requires it. Existing customers of the bank are identified first and then taken through the verification their record requires.
How is a digital fixed deposit different from opening one at a branch?
The deposit contract, the interest liability and the deposit insurance are identical. What changes is the point of access. A digital fixed deposit is opened through an online journey inside an app, with identity verification, funding and confirmation handled in sequence, instead of through branch paperwork. The money is held by the issuing bank in both cases.
How can a fintech platform offer DCB Bank fixed deposits in its app?
Platforms already integrated with the Blostem SDK can enable DCB Bank through configuration, without a new integration or an app release. Platforms that have not yet integrated complete a single API integration covering discovery, KYC, payment, booking and servicing across every issuer on the platform. Blostem publishes integration documentation and provides sandbox access.
Who holds the money in a fixed deposit opened through a fintech app?
The issuing bank holds the deposit. It sits on the bank's balance sheet as a liability to the depositor. The fintech platform provides the interface and Blostem provides the distribution and technology layer between the platform and the bank. Neither the platform nor Blostem holds the depositor's funds.