Personal Loan SDK for Fintech Apps
Embedded personal lending, launched on your platform in weeks.
The intelligent lending infrastructure for partners and lenders. One SDK carries a borrower from mobile number to disbursal — inside your own branded flow, against a whole panel of regulated lenders.
From 10%
Interest rate p.a.
3–60 mo
Tenure, borrower's choice
₹50k–₹25L
Loan amount
In minutes
Quick approval
What Is a Personal Loan SDK?
A personal loan SDK is a ready-made integration that lets a fintech app or platform in India offer personal loans inside its own branded flow. With Blostem's personal loan API, one consented application is matched against each lender's own policy across a multi-lender personal loan panel. Regulated banks and NBFCs are the lenders and make every credit decision; Blostem is the technology layer, acting as the lending service provider (LSP).
Updated on

- 1Verifies the borrowerMobile, PAN and identity checks inside your app
- 2Takes bureau consentAsked before any credit bureau is checked
- 3Matches the lendersOne application against each lender's own policy
- 4Ranks the offersKey facts shown before anything is accepted
- 5Money disbursedThe chosen lender pays into their bank account
The embedded-finance layer India's fintechs already trust.
One integration puts a lending product in front of millions — through the same distribution network already live on Blostem, and a regulated lending & custody stack behind it.






Want this partner network behind a lending product in your app?
Talk to our lending teamOne application. All lenders. Nobody leaves empty handed.
Blostem is the lending service provider (LSP) layer between your users and a panel of regulated lenders. One consented application is scored against every lender's own policy at once — so borrowers only see who will fund them.
70–90%
Approval coverage
Across a multi-lender panel, against 40–60% on any single lender — the same top of funnel, three in ten more borrowers funded.
<10 sec
To a ranked offer set
From consent to real, policy-matched offers, inside your own app. No callback queue, no "we'll get back to you".
1 SDK
No lending licence
No lender-by-lender build, no loan on your books, and no credit policy of your own to run.
Without a panel
One lender says no → the borrower is gone, and your brand wears the rejection.
With Blostem
One lender says no → the next one funds them, same session, no second application.
A “no” from one lender is not a “no” from the market. Blostem turns your biggest source of drop-off into your second-largest source of disbursals.
Intelligent. Neutral. Compliant. Connected.
Five things that hold true whichever side of the marketplace you sit on — and the reason a lending proposition can go live in weeks rather than quarters.
Intelligent decisioning
Evaluate every lender independently, on that lender's own criteria — never a blended score.
Neutral marketplace
Match borrowers with the lender most likely to approve them — never the highest payer.
Fast, easy integration
One lightweight personal loan SDK connects you to a growing lending ecosystem — SSO in, disbursal status back.
Built to scale
Onboard partners and lenders with configurable dashboards and rule engines.
Compliance by design
Consent-first architecture, secure data sharing and complete auditability, end to end.
One integration, both sides of the marketplace, and no lending licence of your own required.
Curious how a multi-lender panel would fit your users?
Book a walkthroughThe core journey, end to end.
Your app hands the user in over SSO — already signed in, contact details prefilled. Identity and KYC first, consent before any bureau pull, then real offers from every lender that can fund them. Ten screens, one sitting, never leaving your app.
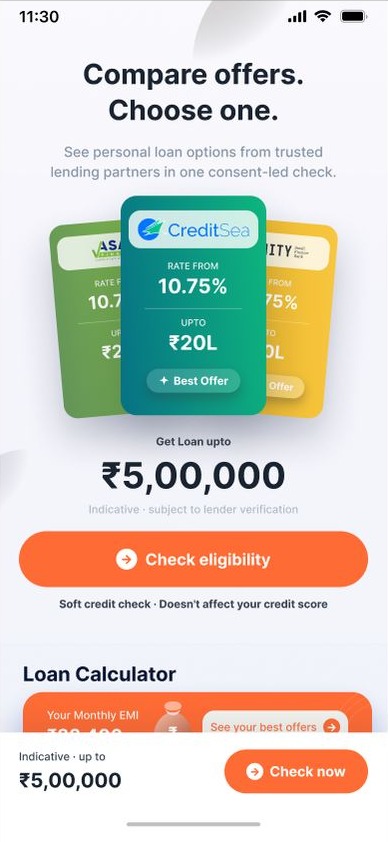
The offer shelf, before the form
The entry screen leads with what the borrower came for — how much, from whom, at what rate. One consent-led check replaces applying to lenders one at a time.
- Best available rate and limit surfaced up front
- Soft credit check, stated before the tap
- EMI calculator, so the ask is shaped before the application
Screens captured from the live build · sample data · lender names, rates and eligibility criteria shown are illustrative
You own the customer. We run the lending stack.
Nothing about the borrower relationship leaves your app, and nothing about credit policy lands on your desk. Here is exactly where the line sits.
Your side
The platform
- Your brand, your colours, your entry point
- SSO handoff with contact details prefilled
- Where and when the offer surfaces in your app
- Loan status and repayment views back in your product
Our side
The Blostem SDK
- Identity, PAN and KYC in one sitting, in-app
- Consent capture before any bureau pull
- Per-lender eligibility, ranked offers, KFS and handoff
- Configurable dashboards, rule engines and audit trail
Lender side
The regulated partner
- Their own credit policy and gating criteria
- Underwriting, sanction and the final credit decision
- Rate, fees, disbursal to the borrower's bank account
- Servicing, repayment and the loan on their books
- White-label · no redirect
- Consent-first architecture
- Key Fact Statement before acceptance
- Only the chosen lender receives data
- Complete auditability
Want to map this split against your own product and team?
Talk it through with usHow to Add Personal Loans to Your App with Blostem
Five steps from first call to live lending in your brand, live in weeks. Regulated lenders make every credit decision, so your app needs no lending licence.
Book a walkthrough and scope your launch
We go through your users, your stack and the lender panel, and plan the journey you want to offer.
Embed the SDK with single sign-on
Add the SDK to your app. Users arrive over SSO with their contact details prefilled, inside your own branded flow.
Collect one consented application
The user gives consent on a dedicated screen before a soft bureau check, then fills in one application.
Match the user to the lender panel
The application is checked against each lender’s own criteria at once, and the user sees real offers. The lender the user chooses makes the credit decision.
The lender disburses, and you go live in weeks
The user reviews the Key Fact Statement before accepting, and the lender disburses the loan. Your app holds no loan on its books.
Build in-house, tie up with one lender, or use Blostem?
Swipe to compare
| Factor | Build in-house | Direct tie-up with one lender | Blostem |
|---|---|---|---|
| Time to launch | Months for each lender | Months for one lender | In weeks |
| Lenders per application | Only the lenders you sign one by one | One, so users outside its policy are declined | A panel of regulated banks and NBFCs |
| Consent, bureau check and Key Fact Statement | You build them | The lender’s own flow | Built into the journey |
| Team you need | Dedicated product, engineering and compliance team | Engineers to build and maintain one lender’s integration | Your app team embeds the SDK |
| Who lends and decides | The lender you partner with | That lender | The lender the user chooses; Blostem acts as the lending service provider (LSP) |
The eight that come up in almost every walkthrough — licensing, coverage, consent, and who decides what.
What partner teams ask first.
Frequently Asked Questions
Lending, embedded in your product.
Book a walkthrough and we will take your team through the SDK handoff, the consent and decisioning flow, and a launch plan tailored to your stack.
- White-label · multi-lender
- www.blostem.com
- Noida · Gurgaon · Delhi