Blostem × Techwealth Partnership Launch at GFF 2026: Digital Bonds Now Available on the Blostem SDK
Digital bonds are now live on the Blostem SDK with Techwealth. Fintech and wealth apps can offer bonds next to FDs and RDs through one API integration.
Key takeaways
- Digital bonds are now live on the Blostem SDK, launched with Techwealth at Global Fintech Fest 2026.
- Platforms can offer FDs, RDs and bonds through one API integration, as a single fixed-income shelf.
- Bond orders are executed by Techwealth, a SEBI-registered stock broker that runs the online bond platform TheFixedIncome.
- Bonds are not deposits: they carry market, credit and default risks and are not covered by DICGC.
What Went Live with Digital Bonds at GFF 2026?
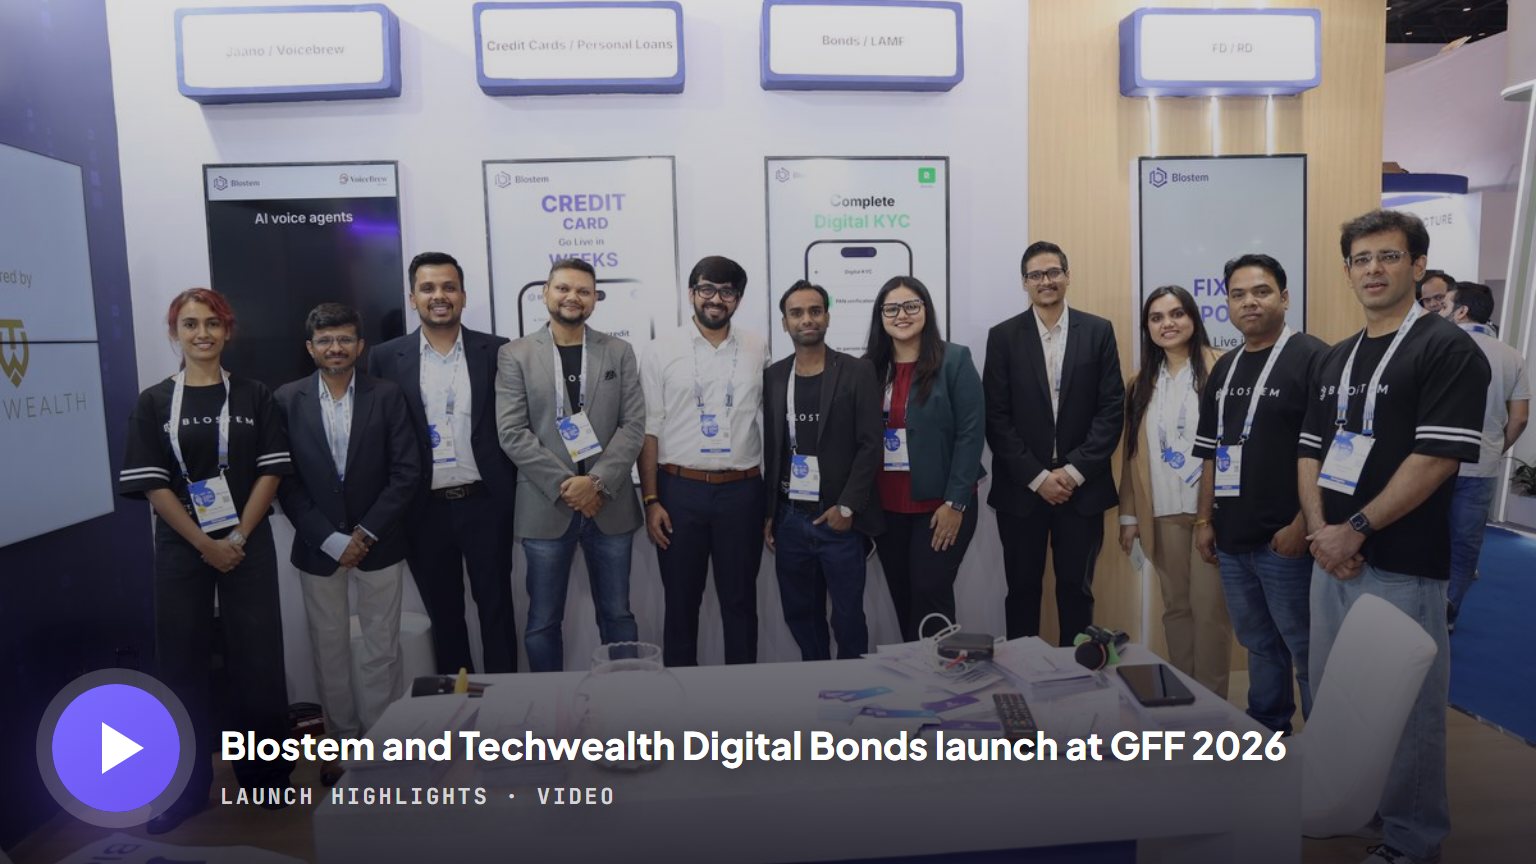
The story behind the collaboration and the moment the partnership was unveiled at Global Fintech Fest 2026. Opens on LinkedIn.
Deposits built the base of Blostem's fixed-income offering. Bonds are the next step. At Global Fintech Fest 2026, held at Jio World Convention Centre in Mumbai from 9 to 11 September 2026, Blostem and Techwealth launched a digital bond journey that platforms can embed in their existing customer experience. Blostem exhibited at Booth J18 and J20 in Pavilion Hall, where bonds sat on the same wall as fixed deposits and recurring deposits.
The partnership pairs Techwealth's experience in India's bond market with Blostem's embedded finance infrastructure. For an end customer, it means a simpler way to discover and invest in bonds inside an app they already use. For a platform, it means a bond product without a separate build.
Why Techwealth?
Bonds are only as good as the platform that sources, executes and settles them. Techwealth brings a regulated bond platform with an established investor base.
- Founded in 2019 (TheFixedIncome)
- 2,00,000+ users on the platform
- ₹1,980 crore+ of investments facilitated
- Member of BSE and NSE
Figures as published by TheFixedIncome, as of 9 October 2026.
Techwealth Capital Services Private Limited runs TheFixedIncome, an online bond investment platform based in Ahmedabad. It is registered with SEBI as a stock broker (registration INZ000312335) and is a member of BSE and NSE. The platform offers bank bonds, PSU bonds, government guaranteed bonds, corporate bonds, tax-free bonds, government securities and fixed deposits, and reports a community of more than 2,00,000 users and over ₹1,980 crore of investments facilitated. (Source: TheFixedIncome, as of 9 October 2026.)
What Are Digital Bonds?
A digital bond is an ordinary listed bond, bought and held through an online journey instead of a broker's paperwork. The instrument is the same: a government security, a PSU bond or a corporate bond with a fixed coupon and maturity. What changes is access. The investor discovers the bond, completes KYC, pays and tracks the holding inside an app, which the platform connects through a bond API integration.
How Are Online Bond Platforms Regulated in India?
SEBI introduced a regulatory framework for online bond platform providers (OBPPs) in November 2022, under the SEBI (Issue and Listing of Non-Convertible Securities) Regulations, 2021. Entities that operate online bond platforms must be registered as stock brokers in the debt segment of a stock exchange. In August 2026, SEBI updated the framework to let OBPPs also offer products regulated by IFSCA and capital gains bonds issued under section 54EC. (Source: SEBI circular, 14 August 2026.)
In the Blostem and Techwealth model, bond orders are executed through Techwealth as the partner OBPP, payments flow to the OBPP and trades clear through the exchange. Blostem provides the embedded journey and technology layer inside the partner platform's app.
How Can Fintechs Offer Bonds Through the Blostem SDK?
The Blostem SDK covers the bond journey end to end, inside the partner's own app:
- Curated shelf. Users arrive through SSO with their details prefilled and see bonds filtered by yield, safety or primary issues.
- Bond details. Yield to maturity, coupon, minimum investment and maturity date, with the full dated payout schedule shown before purchase.
- Investment calculator. Choosing lots shows the amount invested, annual interest, total interest and maturity amount.
- KYC. PAN, address, bank and demat details are confirmed, in-person verification runs on the same screen and the form is e-signed, producing a KRA-portable KYC.
- Payment and settlement. Payment flows to the OBPP and the trade clears through the exchange, with each stage tracked in the app.
- Holdings and exits. Current value, interest earned and every holding in one view. A sell request goes to the partner OBPP's dealer desk, which provides quotes.
Because the same SDK already carries fixed deposits and recurring deposits, a platform can present a single fixed-income shelf rather than three separate products. Read how deposits work on the same rails in our posts on the DCB Bank and Indian Overseas Bank launches from GFF 2026.
What Do Digital Bonds Mean for Fintech and Wealth Platforms?
- A complete fixed-income shelf. FDs, RDs and bonds side by side, through one API integration.
- Room to serve more goals. Investors looking beyond deposits can stay in your app instead of moving to another platform.
- No product or operations build. Sourcing, execution and settlement sit with the regulated partner.
- Your brand, your journey. The bond experience is embedded in your existing customer experience.
Frequently Asked Questions
What are digital bonds?
Digital bonds are ordinary listed bonds, such as government securities, PSU bonds and corporate bonds, bought and held through an online journey instead of through a broker's paperwork. The bond itself does not change. What changes is how an investor discovers it, completes KYC, pays and tracks it.
Are bonds insured like fixed deposits?
No. DICGC deposit insurance covers bank deposits only, up to Rs 5 lakh per depositor per bank. Bonds are not deposits and are not covered by DICGC. A bond's repayment depends on the issuer, which is why credit ratings and issuer quality matter when choosing one.
Are bond returns guaranteed?
No. A bond pays the coupon and principal agreed at issue, but fixed returns are not guaranteed returns. Bonds carry market, credit and default risks, and the price of a bond can change before maturity. Investors should read all offer-related documents before investing.
Who is Techwealth?
Techwealth Capital Services Private Limited runs TheFixedIncome, an online bond investment platform founded in 2019 and based in Ahmedabad. It is registered with SEBI as a stock broker (registration INZ000312335) and is a member of BSE and NSE. It offers bank bonds, PSU bonds, government guaranteed bonds, corporate bonds, tax-free bonds, government securities and fixed deposits.
Can fintech and wealth platforms add digital bonds to their apps?
Yes. Fintech, wealth and consumer platforms can add digital bonds to their apps through API integration with Blostem, covering bond discovery, KYC, payment, settlement and holdings. Bond orders are executed by Techwealth as the partner online bond platform provider, so the platform does not need its own bond API stack or broking setup.
How can a fintech or wealth platform offer bonds in its app?
Through the Blostem SDK, a platform can add a digital bond journey to its existing app: a curated bond shelf, bond details with the full payout schedule, KYC, payment and a holdings view. Bond orders are executed by the partner online bond platform provider and settle through the exchange, so the platform does not need to build the product and operations stack itself.
What is the difference between a fixed deposit and a bond?
A fixed deposit is a deposit with a bank or NBFC that pays a fixed rate and, for bank deposits, is covered by DICGC up to Rs 5 lakh per depositor per bank. A bond is a listed debt security issued by a government, PSU or company. It pays a coupon, can be sold on the market before maturity, and carries market, credit and default risks instead of deposit insurance.